
What Matters Most
- Share only what's needed. Start with relevant financial reports rather than unrestricted access to accounting files.
- Protect sensitive information. Use confidentiality agreements, appropriate redactions, and secure document-sharing methods.
- Increase access gradually. Provide more detailed records as due diligence progresses and the buyer's needs become clear.
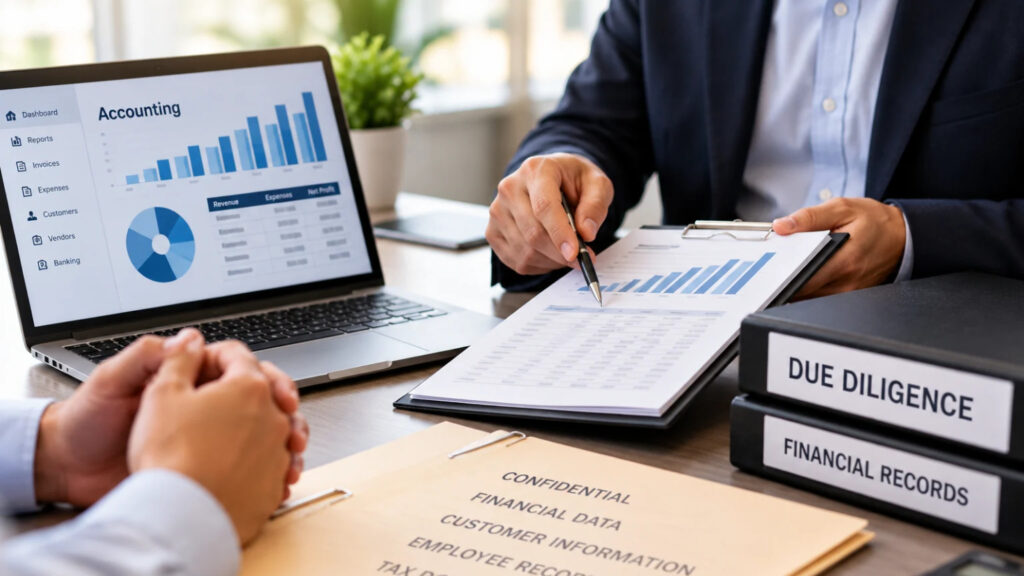
A potential buyer has asked to review your business’s accounting records. You want the sale to progress, but you’re not comfortable sharing years of sensitive financial information before knowing how it will be used.
That concern is reasonable.
A serious buyer needs reliable financial information to assess a business. However, accounting files can contain much more than revenue, expenses, and profit figures. They may also reveal employee compensation, customer information, bank account details, tax identification numbers, and confidential operating records.
Once sensitive information has been shared, controlling its future use becomes more difficult.
This is one reason business owners may work with bookkeeping services in Long Island, NY before entering the due diligence process.
The objective is not to withhold information a legitimate buyer needs. It is to provide appropriate records at the right stage, protect sensitive details, and maintain a clear record of what has been disclosed.
Why Sharing Accounting Files Requires Careful Planning
Buyers may request a complete QuickBooks file, accounting backup, or direct access to a bookkeeping system because it simplifies their review.
For the seller, however, unrestricted access can create unnecessary exposure.
Depending on the software and permissions, accounting records may include detailed transaction histories, customer and vendor information, employee pay rates, internal notes, and other data unrelated to the buyer’s immediate questions.
If negotiations end without a sale, the buyer may still possess copies of that information.
This creates risks involving privacy, commercial confidentiality, employee information, and future negotiations.
The Federal Trade Commission’s guidance on small business cybersecurity recommends controlling access to sensitive data, protecting information with encryption, and sharing it only with people who have a legitimate need.
The IRS also provides guidance on the use of electronic accounting software records, including the importance of retaining reliable underlying records for tax examinations.
Although an IRS examination is different from a business sale, the distinction is useful: preparing selected reports for a buyer should not involve improperly changing or compromising the company’s original accounting records.
Seven Questions to Ask Before Sharing Accounting Files
1. What Financial Information Does the Buyer Actually Need?
Start by asking the buyer to identify the records needed and explain their purpose.
During preliminary discussions, buyers may be able to evaluate a business using documents such as:
- Profit and loss statements.
- Balance sheets and cash flow reports.
- Historical tax returns.
- Accounts receivable and payable summaries.
- Revenue trends and customer concentration reports.
- Debt and major expense schedules.
The appropriate level of detail depends on the transaction and its stage.
A buyer conducting confirmatory due diligence may eventually need transaction-level records or supporting documents. That does not mean full accounting-system access is necessary during the first conversation.
A defined document request helps both parties avoid sharing unnecessary information.
2. Has the Buyer Signed an Appropriate Confidentiality Agreement?
Before exchanging commercially sensitive records, discuss a confidentiality agreement with your legal advisor.
A suitable agreement may address:
- How the buyer can use the information.
- Who is authorized to review it.
- Whether advisors and other representatives are covered.
- Restrictions on further disclosure.
- Requirements for secure storage and handling.
- Return or destruction of information if negotiations end.
A confidentiality agreement establishes legal obligations, but it does not physically prevent someone from copying or mishandling data.
It should therefore be combined with practical security controls.
Depending on the transaction, additional protections may be appropriate for competitively sensitive information, customer identities, or employee records.
3. Can You Share Reports Instead of the Complete Accounting File?
Often, yes.
For early financial reviews, exported reports may provide the necessary information without exposing the entire accounting system.
Possible formats include PDF financial statements, carefully prepared spreadsheets, and supporting schedules.
For example, a buyer investigating revenue trends might initially receive monthly sales reports rather than unrestricted access to the underlying accounting database.
However, exported documents still require inspection.
Spreadsheets may contain hidden worksheets, formulas, comments, linked data, or metadata that reveal more information than intended.
Before sharing, review the actual files, not just their visible pages.
Maintain an untouched copy of the original accounting records and prepare separate buyer-facing reports. Do not alter historical entries merely to make financial results appear more favorable.
If a buyer later requires detailed records to verify the financial statements, establish a controlled process for providing them.
4. Have Personal and Sensitive Details Been Protected?
Accounting records often include information that should not be disclosed without a clear reason.
Examples include:
- Social Security numbers and other personal identifiers.
- Employee payroll details.
- Bank account and payment information.
- Customer contact records.
- Vendor pricing and confidential agreements.
- Internal account credentials or access information.
Where suitable, share aggregated information before disclosing individual records.
Employee compensation might initially be summarized by role or department. Customer concentration can sometimes be presented using coded customer identifiers.
The buyer may need more detailed information later, particularly if it affects business valuation or contractual obligations.
Any redaction or anonymization should be clearly explained so the buyer understands the scope of the information provided.
Use proper redaction methods rather than simply covering text visually in a document.
5. Are You Using a Secure Method to Share Documents?
Email attachments may be convenient, but they can be forwarded, downloaded, or stored without the sender retaining meaningful control.
For sensitive due diligence, consider a secure document-sharing platform or virtual data room.
Useful capabilities include:
- Individual user permissions.
- Multifactor authentication.
- Encryption.
- Access logs.
- Document watermarks.
- Download restrictions.
- The ability to revoke access.
These safeguards help reduce unnecessary exposure.
However, no data room can guarantee that an authorized viewer will never retain information. Download restrictions, for example, may not prevent screenshots or other forms of copying.
The objective is to make access more controlled, traceable, and proportionate to the information being reviewed.
For highly sensitive documents, consider additional protections recommended by your transaction advisor.
6. What Stage Has the Sale Process Reached?
The appropriate amount of disclosure usually changes as the transaction progresses.
During an initial discussion, a buyer may need only enough information to determine whether the business fits their investment criteria.
After signing a confidentiality agreement and demonstrating serious interest, the buyer may request more detailed financial reports.
Once the parties reach a letter of intent or another meaningful transaction milestone, due diligence may become more extensive.
However, a signed letter of intent does not automatically justify unrestricted access.
The buyer’s legitimate information needs, the transaction’s structure, confidentiality protections, and the sensitivity of the records should determine what is shared.
The principle is straightforward: increase access as the process advances and the need for additional detail becomes clear.
7. Has Your Accountant Reviewed the Information?
Before sharing financial records, ask your accountant or financial advisor to review the proposed package.
A professional review may identify:
- Unreconciled accounts.
- Unusual or inconsistent journal entries.
- Misclassified expenses.
- Outstanding tax matters.
- One-time business costs.
- Owner distributions requiring explanation.
- Differences between financial reports and tax filings.
These issues do not necessarily indicate serious financial problems, but unexplained figures can create confusion during negotiations.
A buyer-facing financial package should present accurate information with enough context for proper interpretation.
Accountants can help organize schedules, explain legitimate adjustments, and identify records that require additional protection.
They should not alter original accounting data or create misleading financial presentations.
Why Controlled Sharing Is Better Than Unrestricted Access
Some business owners worry that setting boundaries will discourage a buyer.
Reasonable information controls, however, can support an organized due diligence process.
Consider a business owner who provides unrestricted access to an accounting file before preparing an explanation of owner-related expenses.
The buyer notices several unusual transactions and questions the company’s reported profitability.
Those entries may have legitimate explanations, but presenting them without context can create avoidable confusion.
A properly prepared package could identify the transactions, explain their treatment, and provide supporting records when requested.
The goal is transparency with appropriate organization, not withholding material information.
A credible buyer should receive the records necessary to evaluate the business. The seller should retain reasonable control over how sensitive information is disclosed.
Comparing Ways to Share Accounting Records
Different sharing methods provide different levels of detail and control.
| Sharing Method | What the Buyer Receives | Main Risk | Suitable Stage |
|---|---|---|---|
| PDF financial reports | Financial statements and summaries | Limited detail may require follow-up | Early review |
| Redacted spreadsheet exports | Selected transaction details and analysis | Hidden data or insufficient redaction | Focused due diligence |
| Controlled data room | Organized documents with defined permissions | Incorrect settings or retained copies | Serious negotiations |
| Native accounting file or system access | Extensive accounting data and transaction history | Greater confidentiality and security exposure | Later diligence when justified |
No method is appropriate for every sale.
The best choice depends on the buyer’s request, the sensitivity of the records, the stage of negotiations, and the protections available.
Three Steps to Take Before Sending Any Accounting Records
Prepare a Staged Document List
Identify the financial statements, tax returns, debt schedules, customer concentration information, and other records likely to be requested.
Separate documents suitable for initial discussions from those requiring stronger confidentiality protections or later-stage access.
Reconcile and Explain Your Reports
Review key accounts before distributing financial information.
Prepare clear explanations for unusual entries, owner-related expenses, accounting methods, and legitimate financial adjustments.
A consistent, accurate set of records helps buyers understand the business without unnecessary confusion.
Control Access and Maintain a Disclosure Log
Use a secure sharing method and identify who is permitted to view each document.
Keep a record of the information disclosed, its recipient, the disclosure date, and any applicable restrictions.
Review access permissions as negotiations progress and revoke unnecessary access when appropriate.
Remember that revoking access cannot necessarily retrieve copies already downloaded.
Protect the Business While Keeping the Sale Moving
Selling a business requires balancing transparency with confidentiality.
Potential buyers need dependable financial information. Business owners need to protect employee privacy, customer relationships, sensitive records, and their negotiating position.
The best approach is neither unrestricted access nor unnecessary secrecy.
Ask clear questions, prepare accurate records, use appropriate safeguards, and increase disclosure as the transaction progresses.
Before sending extensive accounting files, involve your accountant and, where appropriate, your legal advisor.
A disciplined process can help protect the business while giving a serious buyer the information needed to make an informed decision.
Sources
- Federal Trade Commission: Cybersecurity for Small Business (opens in a new tab)Protecting sensitive business information through access controls, encryption, authentication, and secure data-sharing practices.
- Internal Revenue Service: Use of Electronic Accounting Software Records (opens in a new tab)The importance of retaining reliable electronic accounting records and understanding the information contained in accounting software files.
- Internal Revenue Service: Recordkeeping (opens in a new tab)Maintaining complete financial records and supporting documentation for business income, expenses, and tax reporting.
Was this helpful?
What could be better? (optional)
Leave a Reply