
You already know the feeling. An audit is coming, the request list keeps growing, and every missing document starts to feel larger than it is. One unclear account balance can turn into three follow up questions. One weak process can pull in your controller, your operations team, and leadership all at once. The pressure is not just about numbers. It is about credibility, timing, and whether your financial reporting will hold up under review. For businesses seeking stronger oversight, fractional controller services in Sylmar can help reduce risk and improve audit readiness.
That is where accounting firms help. Good audit preparation does not mean dressing up weak records at the last minute. It means getting your books, support, controls, and communication in shape so the audit can move with fewer surprises. How Accounting Firms Provide Assurance Through Audit Preparation comes down to reducing gaps before the auditor finds them, building support for key judgments, and helping you present a financial story that is complete and consistent.
Audit preparation gives structure to financial assurance services
Assurance starts long before fieldwork. Auditors are expected to plan the engagement around risk, material accounts, relevant assertions, and the company’s internal control environment. The PCAOB’s guidance on audit planning makes that clear. If your records are disorganized or your explanations change from meeting to meeting, the audit gets slower, more expensive, and more tense.
Accounting firms step in before that happens. They review trial balances, reconcile key accounts, trace unusual transactions, and gather the support that auditors will ask for anyway. Revenue recognition, accruals, debt agreements, equity activity, and related party transactions often need extra attention because they carry more judgment and more risk. If your team has ever said, “We know the number is right, we just need time to prove it,” then you have already seen the problem. Audits run on evidence, not confidence.
This is why audit readiness support matters. It turns scattered records into a clean package. It also helps management spot weaknesses that are easy to miss during a busy close cycle, such as unsupported manual journal entries, stale reconciliations, or approvals that exist in practice but were never documented.
Weak preparation raises audit risk and drains internal time
The cost of poor preparation rarely shows up in one obvious line item. It shows up in rework, delays, expanded testing, and leadership distraction. A controller may spend hours answering questions that could have been avoided with one complete memo. A CFO may need to explain why estimates changed because assumptions were not documented at the time they were made. The audit committee may lose confidence when the same issues keep resurfacing year after year.
That communication piece matters more than many companies expect. The PCAOB has highlighted the role of audit committee communications in making sure significant risks, judgments, and difficulties are discussed clearly. Their spotlight on conversations with audit committee chairs reinforces the same point. Assurance is not only about whether records exist. It is also about whether management can explain them in a way that is consistent, timely, and credible.
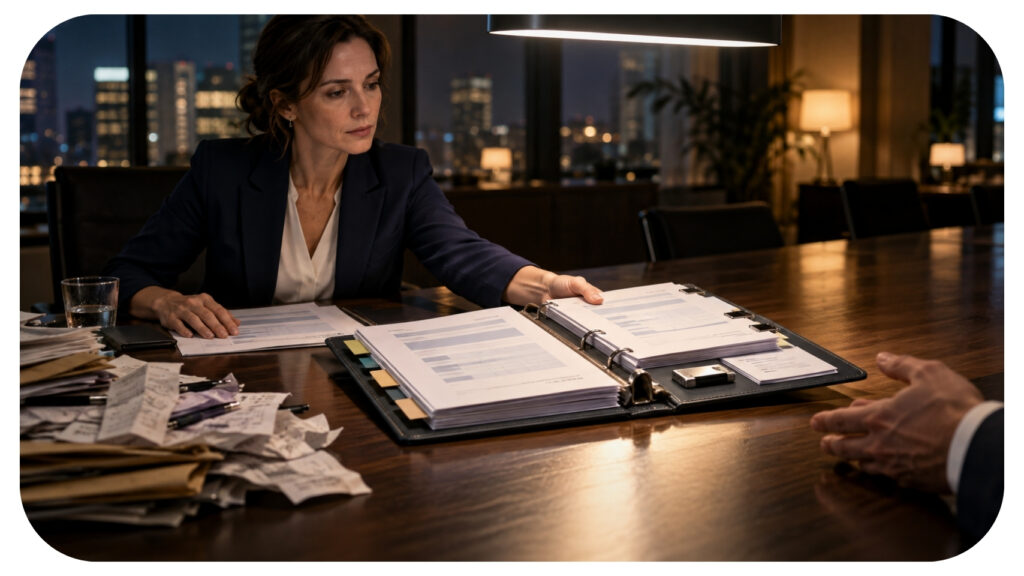
Picture a common scenario. Your company closes the year with a large spike in revenue from a new contract structure. The accounting team understands the business reason, but there is no memo tying the contract terms to the accounting treatment. During the audit, that gap becomes a risk area. More samples get selected. More meetings get scheduled. More people get pulled in. The issue may still resolve cleanly, but it takes longer and costs more because the support came after the question instead of before it.
Professional audit preparation creates cleaner evidence and steadier communication
Accounting firms provide assurance through preparation by doing two things at once. They strengthen the underlying accounting, and they improve how that accounting is presented to auditors and governance teams. That can include cleaning up account reconciliations, drafting technical accounting memos, organizing PBC schedules, reviewing disclosures, and identifying control gaps before they become formal findings.
This kind of accounting and tax support also helps when the pressure is not purely audit related. Tax accruals, uncertain positions, deferred tax balances, and legal entity activity often affect both the audit and the tax provision. If those areas are handled in isolation, inconsistencies can surface fast. A coordinated review lowers that risk.
DIY audit prep and firm led preparation produce different outcomes
| Approach | What It Often Looks Like | Common Risk | Likely Result |
|---|---|---|---|
| Internal team only | Support is gathered during the audit, reconciliations are completed late, technical positions are explained verbally | Missing documentation, inconsistent answers, expanded audit testing | Delays, higher stress, more follow up requests |
| Accounting firm assisted prep | Accounts are reconciled in advance, key judgments are documented, PBC lists are organized before fieldwork | Fewer unresolved items at the start of the audit | Faster response times, clearer support, smoother audit flow |
| Reactive cleanup after issues surface | Errors are corrected mid audit, schedules are rebuilt under deadline pressure | Control concerns, strained auditor confidence, possible committee escalation | Higher costs and weaker overall assurance |
Three steps improve audit readiness right away
1. Identify the accounts that carry judgment. Start with revenue, reserves, debt, leases, equity, and related party activity. These areas usually create the hardest audit questions because they depend on estimates, timing, or contract terms. Gather support now, not after the request list arrives.
2. Test your documentation the way an auditor would. Pick a few material balances and ask whether an outside reviewer could follow the number from the general ledger to the source support without verbal explanation. If the answer is no, the file is not ready. This is one of the clearest ways financial statement audit preparation reduces friction.
3. Align accounting, tax, and governance communication. Make sure the numbers in your workpapers match the story being told to leadership and the audit committee. If an estimate changed, document why. If a control failed, document what was fixed. Strong accounting support is not only technical. It is consistent.
Audit pressure can make even organized teams feel exposed. That does not mean your company is failing. It means the process is asking for proof, discipline, and clear communication all at once. When accounting firms prepare your records before the audit starts, they help turn that pressure into something manageable. The result is stronger assurance, cleaner support, and fewer surprises when scrutiny is highest.
If you need help with accounting and tax matters tied to audit readiness, now is the time to get your records and documentation in order.
Leave a Reply