
Key Takeaways
- International cash flow affects liquidity, profit margins, supplier relationships, and planning.
- Tracking currency exposure helps businesses identify potential cost changes before payments are due.
- Payment providers should be assessed on total cost, timing, visibility, controls, and recordkeeping.
- A documented process reduces avoidable delays, surprise fees, and reconciliation problems.
- Regular reviews help businesses match payment methods to the currency, destination, urgency, and risk of each transaction.
For a growing business, selling or buying internationally can create opportunities, but it also adds financial complexity. Customer payments may arrive in one currency while inventory, contractors, taxes, and software costs must be paid in another. A multi currency account for business can be an option to consider when a company needs clearer separation of balances across different markets.
Strong cross-border cash flow management is not about predicting every exchange-rate move. It is about knowing what money is expected, what obligations are approaching, how long transfers may take, and what each payment will cost in practical terms.
Why Cross-Border Cash Flow Feels Harder
Domestic payments usually follow familiar schedules, currencies, and banking practices. International transactions can involve conversion rates, transfer fees, intermediary charges, local recipient requirements, payment cut-off times, and settlement delays. Each added step can make it harder to know precisely when funds are available.
Consider a U.S. online retailer that receives card payments from customers but pays an overseas supplier before its next sales payout settles. Even if the retailer appears profitable on paper, it can face a short-term cash gap that affects inventory orders, contractor invoices, or payroll. The answer is a repeatable process, not simply another payment account.
How Currency Exposure Changes Business Results
Currency exposure is the possibility that an exchange-rate change will alter the home-currency value of money a business expects to receive or needs to pay. It can appear in several ways:
- Transaction exposure: An invoice is due soon in a foreign currency, so its actual cost or value may change before settlement.
- Operating exposure: Regular overseas purchasing or sales can make everyday margins more sensitive to currency movements.
- Translation exposure: Foreign-currency balances may need to be converted for internal reporting or financial statements.
A supplier invoice priced in euros may cost more dollars by the payment date than it did when the order was placed. Small businesses do not necessarily need complex hedging arrangements to respond. A useful first step is to track the currency, amount, due date, and estimated home-currency value of every significant international obligation.
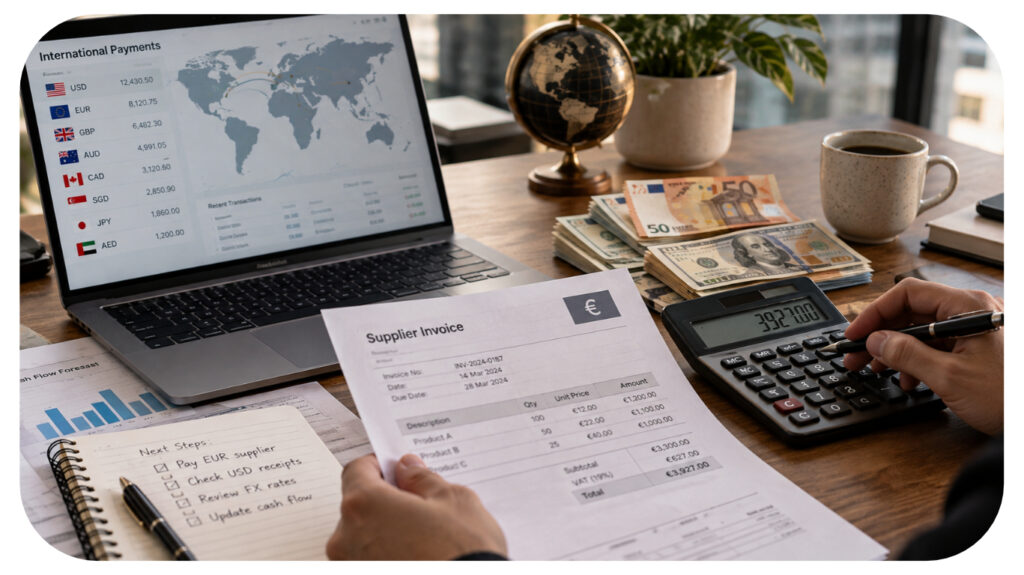
Photorealistic macro close-up of a business finance desk showing a printed foreign-currency supplier invoice beside a calculator and a small stack of mixed euro and U.S. dollar notes, with sharp paper texture, currency details, and shallow depth of field against a softly blurred office background.
Build a Simple International Payment Map
Create a one-page worksheet that shows where money enters and leaves the business. Update it when a new customer market, supplier, contractor, or payment method is added. Include the following areas:
- Customer income: Note customer currencies, expected receipt dates, processing times, and any conversion point.
- Supplier costs: Record each supplier’s preferred currency, invoice terms, fees, and payment instructions.
- Contractor payments: Identify recurring, project-based, and urgent obligations separately.
- Taxes and reporting: Confirm the currency used for invoices, accounting records, and required tax calculations.
- Cash reserves: Decide how much should remain available for near-term obligations in each relevant currency.
What to Check Before Choosing a Payment Provider
A provider should be evaluated by more than its advertised transfer fee. Review the exchange-rate margin, sending and receiving fees, withdrawal charges, supported currencies, normal delivery times, payment tracking, and the quality of transaction records. Also check user permissions, approval workflows, account limits, and the process for resolving a delayed payment.
These details matter because research on small-business payment decisions identifies trust, speed, and cost transparency as important factors in selecting cross-border payment providers. For a small company, a clear status update and a predictable arrival date can be as valuable as a lower headline price.
Protect Working Capital and Payment Timing
Money that is expected or in transit is not the same as cash available for use. Build a rolling cash forecast covering at least the next four to eight weeks, then compare expected incoming funds with scheduled foreign-currency payments. This creates time to adjust before a shortfall becomes urgent.
A Weekly International Cash Review
- List international customer receipts expected during the week.
- List supplier, contractor, and other foreign-currency payments due.
- Estimate any currency conversions required.
- Flag timing gaps, unusually large expenses, and payments that need approval.
Grouping routine payments can reduce administrative effort, but urgent obligations should remain separate. Paying earlier may offer certainty, while holding cash longer may preserve flexibility. The appropriate choice depends on supplier terms, available liquidity, and the cost of a delay.
Make Reconciliation Less Painful
International transactions often create mismatches between the original invoice, the transferred amount, the conversion rate, fees, and the date funds arrive. A consistent recordkeeping routine prevents these differences from becoming a month-end mystery.
- Use one reference number across the invoice, purchase order, payment, and confirmation.
- Record the exchange rate and the currency converted for each transaction.
- Separate invoice amounts from transfer fees and currency gains or losses in accounting records.
- Reconcile incoming and outgoing international payments on a fixed schedule.
- Assign responsibility for reviewing unmatched transactions every week.
Add Basic Risk and Compliance Controls
Faster payment options do not eliminate the need for careful review. Verify the supplier and contractor details before sending funds, especially if bank details have changed. Use dual approval for large or unusual payments, set limits for new recipients, and keep personal and business money separate.
Before entering a new market, review relevant tax, reporting, sanctions, and customer-verification obligations. Retain invoices, contracts, approvals, and payment confirmations in an organized system. These records support both financial oversight and a faster response if a payment is questioned.
A 30-Day Action Plan for Better Cash Flow
Week One: Gather the Numbers
List every country involved in sales, purchasing, payroll, and contracting. Record the currency, value, frequency, payment terms, and timing of each flow. Identify the three most expensive or unpredictable payment paths.
Week Two: Find the Friction
Compare promised receipt dates with actual arrival dates. Review exchange costs, unexpected fees, manual approval steps, and the time required to match payments to invoices.
Week Three: Set New Rules
Create approval thresholds, choose a regular reconciliation day, define preferred payment methods by market, and set target cash reserves for essential currencies.
Week Four: Test and Improve
Follow one customer receipt and one supplier payment from start to finish. Measure cost, timing, visibility, and recordkeeping effort. This approach reflects the broader shift described in cross-border payment workflows, where value increasingly comes from connecting payments with treasury, invoicing, and reconciliation processes.
Final Thoughts
Cross-border cash flow does not need to be mysterious. A payment map, regular currency review, realistic timing assumptions, clear approvals, and consistent reconciliation can give a small business more control. The best process is not necessarily the most complex. It is the one that makes costs visible, keeps payment timing clear, and supports better daily decisions.
Leave a Reply